
Emergency Loans Online for Unexpected Expenses
We offer payday and installment loans depending on your state. Before you apply, compare the repayment schedule, borrowing cost and steps that affect when funds may become available. Emergency loans can help pay for car repairs, medical care, urgent home repairs, funeral expenses or rent. Amounts, fees and terms follow your state’s law, and every request is reviewed. Bad credit is considered.
- 24/7application access
- 2 loan typespayday or installment
- State lawsets lending limits
- Bad creditconsidered
Approval and funding times are not guaranteed. Availability and terms vary by state and product.
Review our company information and contact details. Confirm licensing and product availability for your state before applying.
- Loan Types
- Costs
- Funding Timing
- Requirements
- State and City Information
- Repayment and Budget Check
- Alternatives
- How to Apply
- FAQs
Video transcript
- 0:00 Car just died? Medical bill? Rent due before payday?
- 0:04 Here’s how emergency loans really work.
- 0:06 Two ways to borrow: installments, or one payment on payday.
- 0:10 Same $1,000. Repay $1,200, or over $2,000.
- 0:14 Six steps to your bank. Funds usually land within one business day of approval.
- 0:19 APR, fees and due dates, before you sign.
- 0:22 Bad credit? Considered. State law? Always.
- 0:25 Instant Cash Advance. Compare first. Then apply.
Which Type of Emergency Loan Fits Your Expense?
The right loan depends on how much you need and how soon you can repay it. The phrase “emergency cash loans” describes why you borrow, not a legal type of loan. If the shortfall comes back every month, a new loan will not fix it; the alternatives below may help more.
Installment Repayment and Single-Payment Borrowing
An installment loan spreads repayment across scheduled payments; each payment and the total cost depend on the loan terms (How Personal Installment Loans Work). Emergency personal loans often use an installment schedule; check the actual term and payment frequency. With a payday loan, you usually repay the amount borrowed plus a fee in one payment on your next payday (How Payday Loans Work). The exact structure depends on your agreement and your state. Compare six common options:
Choose an option to compare repayment, costs and timing. Scroll sideways to see all six options.
- How It Works
- A set amount, repaid in scheduled payments
- Repayment
- Scheduled payments over the loan term
- Costs to Check
- APR, origination fee, total repaid
- Timing Depends On
- Review, signing, bank posting
- Main Risk
- A longer term can raise the total cost
- Next Step
- Installment Loan Repayment
We offer this product depending on your state.
- How It Works
- A small loan due on your next payday
- Repayment
- One payment covering the amount borrowed and the fee
- Costs to Check
- Fee per $100 borrowed and the corresponding APR
- Timing Depends On
- Review, signing, bank posting
- Main Risk
- Renewal fees may leave the principal unchanged
- Next Step
- Payday Loan Repayment and Terms
We offer this product depending on your state.
- How It Works
- Small-dollar loans for members
- Repayment
- Payments on the credit union’s schedule
- Costs to Check
- APR, application fee, membership
- Timing Depends On
- Membership and the credit union’s review
- Main Risk
- Not every credit union offers them
- Next Step
- Ask your local credit union
An alternative to our loans.
- How It Works
- Cash drawn on your card’s line of credit
- Repayment
- Added to your card balance
- Costs to Check
- Cash advance fee, interest from day one
- Timing Depends On
- Your cash limit
- Main Risk
- The balance can grow fast
- Next Step
- Read your card’s cash advance terms
An alternative to our loans.
- How It Works
- Part of wages you have already earned
- Repayment
- Taken from your next paycheck
- Costs to Check
- Expedited transfer fees, tips and subscription charges
- Timing Depends On
- Your employer’s or app’s rules
- Main Risk
- A smaller next paycheck
- Next Step
- Ask your payroll department
An alternative to our loans.
- How It Works
- A payment plan spreads out the bill; assistance may cover part of it
- Repayment
- Payments under the plan; some assistance does not require repayment
- Costs to Check
- Plan fees, program eligibility
- Timing Depends On
- The provider’s processing time
- Main Risk
- Help may not arrive in time
- Next Step
- Call before the due date
An alternative to our loans.
Not on the list: title loans, pawn loans and buy now, pay later plans are not compared in the tabs above. A title loan uses your car as collateral, so falling behind can cost you the vehicle. Rent due soon? Read Emergency Loans for Rent. Need a larger amount? See Personal Loan Information.
Estimate the Cost Before You Borrow
A low payment does not necessarily mean low-cost emergency loans. Compare the total repayment: the cost of borrowing the same amount can vary with the APR, fees and repayment term.
What the APR, Fees and Total Repayment Tell You
The interest rate is the cost of borrowing the principal, expressed as an annual percentage. It does not include loan fees. The APR also includes certain fees, such as an origination fee, so it is the better number for comparing offers (Interest Rate and APR Explained). If a fee is taken out of the loan, you receive less cash than the principal you repay. A smaller monthly payment over a longer term can raise the total cost. Review the disclosures for applicable fees, including charges for late or returned payments (Personal Installment Loan Fees). Here is the same $1,000 at three APRs:
| Amount Borrowed | Illustrative APR (No Fees) | Monthly Payments | Approximate Monthly Payment | Approximate Total Repayment | Approximate Borrowing Cost |
|---|---|---|---|---|---|
| $1,000 | 36% | 12 | $100.46 | $1,205.55 | $205.55 |
| $1,000 | 99% | 12 | $134.42 | $1,613.03 | $613.03 |
| $1,000 | 160% | 12 | $171.53 | $2,058.39 | $1,058.39 |
These are hypothetical examples, not our rates or a loan offer. They assume equal monthly payments, no fees and a fixed annual interest rate equal to the illustrated APR. Actual costs and terms depend on the product, state and loan agreement. Rounding may change the final payment.
Two Ways to Estimate Borrowing Costs
Use the installment illustration for emergency installment loans repaid in monthly payments. It shows the payment, the cash you receive and the total cost, with or without an upfront fee. Use the single-payment illustration for a loan repaid in one payment: enter the cash you receive, the finance charge and the days until it is due. Results update as you type. Review Rates and Fee Information, then confirm the pricing for your state and product before applying.
Loan Cost Calculator
- $100.46Approximate Monthly Payment
- $1,205.55Total of Installment Payments
- $1,000.00Cash Received
- $0.00Upfront Fee
- $1,000.00Cash After Upfront Fee
- $1,205.55Total Cash Paid
- $205.55Total Borrowing Cost
Assumes a fixed rate and equal monthly periods, with the first payment due in one month. Excludes financed fees, irregular dates, late fees and early payoff adjustments. Fees can make the APR different from the annual interest rate. Check the APR in your loan disclosures.
Hypothetical example: a $50 fee deducted from a $1,000 principal leaves $950 for the expense, while repayments are based on $1,000. Do not add the deducted fee to the installment total again.
- $575.00Amount Due
- $75.00Borrowing Cost
- 391.07%Illustrative Annualized Rate
This annualized fee illustration assumes one payment and no other charges. It is not a personalized APR quote or our product pricing.
Drag a slider or type a value. To use the mouse wheel, first focus the field or slider. Sliders provide a quick selection range; type a value to use the full limits shown above.
Illustration only. These inputs are examples, not our rates, loan limits or an offer. Your loan agreement determines the actual cost and repayment schedule.
Approval and funding times are not guaranteed.
Can Emergency Loan Funds Arrive the Same Day?
Same-day funding is not guaranteed for emergency loans, so do not rely on it without confirming the timing for your application. It depends on when your review is finished, when you sign and when your bank posts the deposit. Funds usually become available within one business day after approval.
From Application to Bank Availability
The table separates review, signing, fund release and bank availability. Each stage can affect timing:
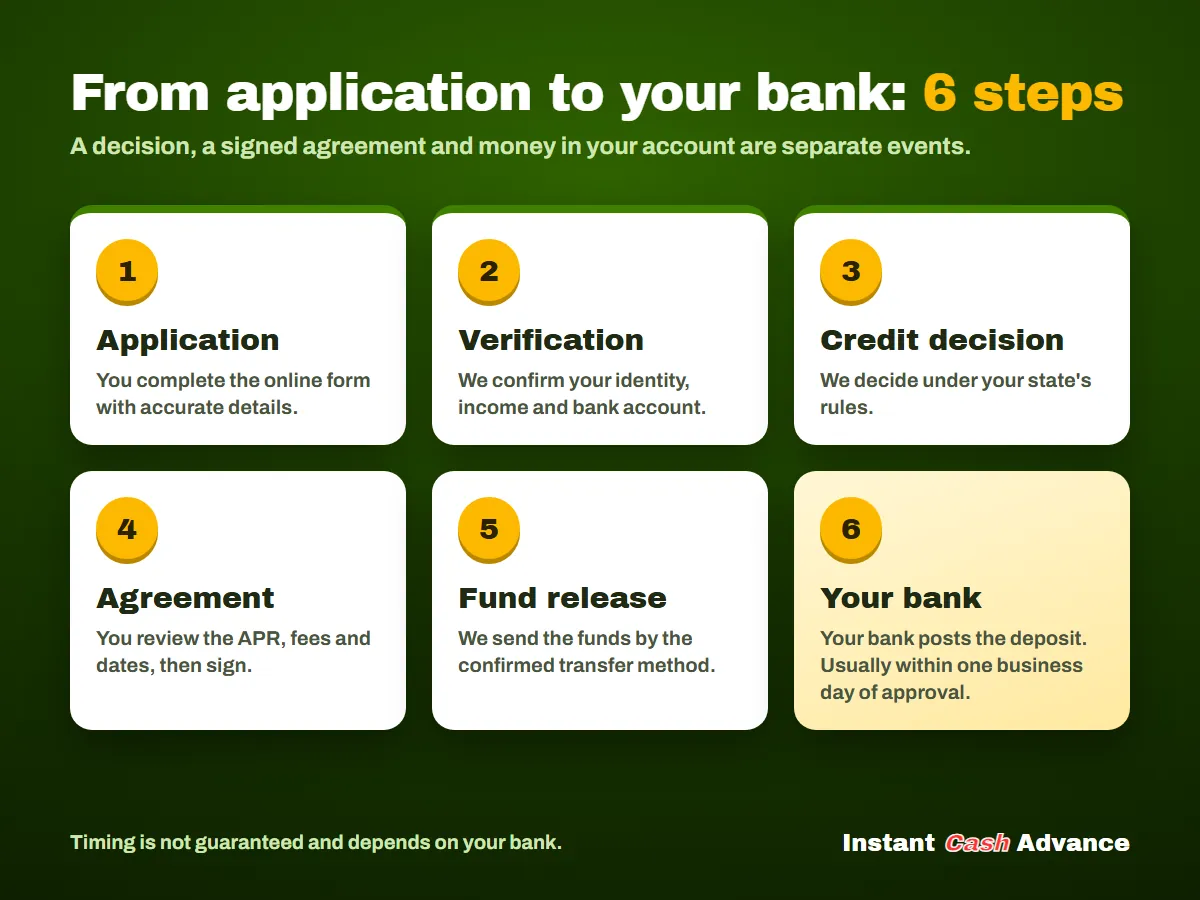
| Stage | Who Acts | What Must Happen | What Can Cause a Delay | Timing to Confirm |
|---|---|---|---|---|
| Application | You | Complete the application with accurate details | Missing or mismatched information | Ask when review starts |
| Verification | Our review team | Confirm your identity, income and bank account | A request for documents or slow responses from data sources | Ask whether documents are still needed |
| Credit Decision | Our review team | Decide on the request under your state’s rules | Extra review of income or existing obligations | Ask when a decision may be available |
| Loan Agreement | You and Instant Cash Advance | Read the disclosures and sign the agreement | An unsigned agreement or a missed signing deadline | Check the signing deadline |
| Fund Release | Instant Cash Advance | Release the funds using the transfer method confirmed for your loan | Cutoff times, weekends and bank holidays | Confirm the transfer method and release timing |
| Bank Availability | Your bank | Post the deposit and make it available | Your bank’s posting schedule or a hold | Usually within one business day after approval; not guaranteed |
A submitted application, an approval decision and money available in your account are separate events.
Weekends, Holidays and Cutoff Times
Same-day emergency loans depend on the review schedule, any applicable cutoff, the transfer method and your bank. Completing an application late in the day, on a weekend or on a holiday may delay the process. For more on timing, read Funding Timing Details.
- What Happens Next
- Funds can be released once review and signing are complete
- What Can Delay Funds
- A document request or a late signature
- What to Confirm
- Which transfer method applies, such as direct deposit, and when the funds may become available
- What Happens Next
- Missing a cutoff may delay release; confirm the next processing opportunity
- What Can Delay Funds
- A weekend or bank holiday before processing resumes
- What to Confirm
- Whether a cutoff applies and which time zone it uses
- What Happens Next
- Application access and transfer processing may follow different schedules
- What Can Delay Funds
- Weekend and holiday availability depends on the transfer method and receiving bank
- What to Confirm
- Whether that is soon enough for your bill
What Do We Review Before Making a Loan Decision?
Review requirements for emergency loans depend on your state and product. We look at identity, residence, income, existing obligations, banking details and credit history to decide whether a loan fits your situation and what terms your state allows.
Documents and Eligibility
Have these ready before you start. This guide does not request personal or bank information; you enter it only on the application page. Read Privacy and Data Use to see how your information is handled.
- What to Prepare
- Any identification documents and identification numbers requested in the application
- Why It Matters
- Fraud checks and your state’s minimum age
- Where to Confirm
- The application
- What to Prepare
- Your current home address
- Why It Matters
- State law governs permitted products, loan limits, fees and repayment terms
- Where to Confirm
- Your state or city page below
- What to Prepare
- Proof of regular income if requested
- Why It Matters
- Payments must fit what you earn
- Where to Confirm
- Confirm accepted income sources before applying
- What to Prepare
- Your rent, loans and regular bills
- Why It Matters
- A new payment must not crowd out essentials
- Where to Confirm
- The budget check in the repayment section
- What to Prepare
- A bank account for the deposit
- Why It Matters
- Where funds go and payments come from
- Where to Confirm
- The account requirements for your state and product
- What to Prepare
- Review the credit inquiry disclosures and any consent requests
- Why It Matters
- Credit review may affect eligibility and loan terms
- Where to Confirm
- The credit inquiry disclosures
Before applying, confirm which loan type is available in your state, whether a hard credit inquiry is required, how repayments are collected and whether additional documents may be requested.
Military borrowers: the Military Lending Act limits covered credit to a 36% Military Annual Percentage Rate (MAPR) for covered service members and dependents, and MAPR can include charges beyond the standard APR. See Military Lending Act, 10 U.S.C. § 987.
Credit Inquiries and Your Credit Score
A soft inquiry does not affect your credit score. A hard inquiry can temporarily lower your credit score (Hard and Soft Credit Inquiries). Before applying, review any credit inquiry disclosures and ask which checks may apply at each stage.
Emergency Loans for Bad Credit: What to Consider
Bad credit does not rule you out, but it does not mean automatic approval either. Applicants with bad credit still need to meet the eligibility requirements for their state and product.
A Low Credit Score Does Not Remove the Review
We look at your income, existing debts and ability to repay as well as your credit history. With bad credit, compare the APR and total repayment carefully before accepting any offer. Check whether a co-signer or joint application is allowed; do not assume either is available. No credit score guarantees approval. Be wary of any lender that promises approval before reviewing your application.
Can You Apply Without a Job?
Not having a job is not the same as having no income. You need regular income you can verify. Confirm which income sources count for your state and product before applying. If you have no reliable way to repay, a payment plan or local assistance is a safer first step than a loan. More on this: Income Options Without a Job.
Explore Loan Information for Your State or City
Emergency loans work differently from state to state. Which loans we offer, the maximum amount, the fees and the repayment terms all depend on the state you live in. Use the links below to explore local information, then confirm current availability and terms before applying. Looking for emergency loans near you? Start with your state to check local information. You can apply online without visiting a branch. A page for your area does not mean every product is available there. To check a lender’s license, find your state financial regulator.
- Alabama
- CaliforniaCities: Los Angeles, Sacramento, San Diego
- ColoradoCities: Denver
- Florida
- Illinois
- Indiana
- Iowa
- Kentucky
- Louisiana
- Maryland
- Mississippi
- Missouri
- NevadaCity: Las Vegas
- New Mexico
- OhioCities: Columbus, Toledo
- Oklahoma
- OregonCity: Portland
- Tennessee
- TexasCities: Dallas, Houston, San Antonio
- Wisconsin
For California payday loans, the check amount is limited to $300 and the fee to 15% of that amount, so a $300 check with the maximum $45 fee leaves $255 in cash (California DFPI).
Plan Repayment Before You Apply
Emergency loans help only if you can repay them on time and still cover your basic costs.
Match the Payment Schedule to Your Budget
Take your next paycheck, subtract rent, food, utilities and other bills due before the following payday, then subtract the loan payment. For a payday loan, use the full amount due, not a monthly figure. If the result is negative, borrow less or try an alternative; a longer term may lower each payment but increase the total cost, depending on the rate and fees.
Include every loan payment due in this period. Do not count an existing payment again if it is already included in bills. A simple budget check, not a credit decision. This check runs in your browser and does not submit a loan application.
If You May Miss a Payment
Contact us before the due date. Your agreement and state law set what options exist and what a late payment costs. Paying only a renewal fee may leave your outstanding principal unchanged (Payday Loan Renewal and Rollover Costs). Taking a new loan to repay an old one can start a debt cycle. Contact Us About Payments.
Alternatives to Borrowing for an Urgent Expense
Before borrowing, check whether savings, a payment plan or assistance could cover the expense. Each option has its own rules and timing, so check them before you rely on one.
- Payment plan with the bill providerHospitals, utilities and landlords may split a bill if you call before it is late. Ask about financial assistance and a payment plan before moving the bill to a loan, and whether late fees still apply.
- Public or local assistancePrograms can help with housing, utilities and food; confirm eligibility, the amount covered and when help would reach the provider. Dial 211 or Explore Financial Assistance.
- Credit union small-dollar loanAsk a credit union about membership, availability, APR, fees and review. See Credit Union Small-Dollar Loan Options.
- Employer advanceAsk whether your employer offers an advance, when you would receive it and what fees apply. Check how it will reduce your next paycheck.
- Agreement with family or friendsAgree on the amount and repayment dates in writing to protect the relationship.
- Emergency fundEven small savings can cover part of the bill and reduce what you borrow.
When a New Loan Could Make the Shortfall Worse
If your regular bills already cost more than you earn, a new payment can deepen the gap. In that case, talk to the companies you owe and look for assistance first. For more ideas, read Ways to Handle an Immediate Cash Need.
How to Apply with Instant Cash Advance
Complete the online application to request one of our emergency loans. Submitting it does not guarantee approval. Here is how it works:
- Check your state. Make sure we offer loans where you live and review the requirements above.
- Fill in the application with accurate personal, income and bank details.
- Wait for a decision. We verify your information and review your request.
- Review and sign. If approved, review the loan type, amount, APR, fees and payment dates before signing. You do not have to accept.
Learn more: How Our Application Process Works and Loan Terms and Conditions.
Approval and funding times are not guaranteed.
Emergency Loan FAQs
Can you borrow emergency money?
Yes, you can borrow money for an unexpected expense, but approval is never automatic. Depending on your state, we offer payday loans repaid in one payment and installment loans repaid over several payments. Every request goes through a review of your identity, income and bank details. Before you apply, check that the full repayment fits your budget and compare the loan types above.
How to get emergency funds immediately?
Applying does not guarantee immediate access to funds, and same-day funding depends on timing. Start with the deadline: call the company you owe and ask for more time or a payment plan, and check local assistance or your own savings. If you still need to borrow, apply with your ID, income and bank details ready, and remember that a decision and a bank deposit happen at different times.
Where can I borrow money urgently?
Banks, credit unions and online lenders like us all offer emergency loans and other short-term credit. Compare three things: the total repayment, whether payments fit your budget and when funds may become available in your account. We offer payday or installment loans depending on your state, so the options we can show you depend on where you live.
Where can I loan money for an emergency?
Borrow only from a company whose name, contact details and loan terms you can verify before you share personal data. Check which products it offers in your state, and find your state financial regulator if you have doubts. Use our state and city pages as a starting point, then confirm current rules and product availability before applying. Review the loan disclosures before signing.
How to get $2000 fast with bad credit?
Whether $2,000 is possible depends on your state’s limits, the loan type and your income, not only on your credit score. Check the available loan type, each payment and the total cost. Approval depends on the product’s eligibility requirements; funding also depends on verification, signing and the transfer process. Read our $2,000 Loan Information page for details.
How can I get a $200 loan?
A $200 loan is usually a small payday or installment loan, and it still goes through a review and must be repaid on schedule. Compare the dollar fee with the $200 you receive, because a small loan can still carry a high APR. If the bill is from a utility or a medical provider, ask about a payment arrangement first. See $200 Loan Information.
Which loan can I get instantly online?
No loan is guaranteed to be approved or funded instantly online. Completing the application, verification, signing and the transfer to your bank are separate steps, and each can take time. Prepare the requested documents and check for follow-up requests to avoid preventable delays. The funding timeline above shows what happens between applying and receiving money.
What is the easiest type of loan to get with bad credit?
No single loan type is the easiest for everyone, and none is guaranteed. Some lenders consider income and bank activity when reviewing applicants with low scores. Compare the APR, fees and total repayment for any offer. Loans secured by a car or other property put that property at risk if you fall behind. Compare the total cost, confirm you can repay and consider the alternatives before applying.
Can I apply for an emergency loan without a job?
You can apply, but you need regular income you can verify, and a job is not the only possible source. Which kinds of income count depends on the product and your state, so confirm that first. If you have no reliable income to repay a loan, a payment plan or local assistance is safer. See Income Options Without a Job.
Can I qualify with a 500 credit score?
A score of 500 does not establish eligibility. The decision depends on the requirements for your state and product and our application review. If you are approved with a low score, the loan may cost more. Review the requirements above, then check the full repayment against your monthly budget.
Will applying affect my credit score?
It depends on the type of inquiry. According to the CFPB, a soft inquiry does not affect your credit score, while a hard inquiry can temporarily lower it. Before applying, review the available credit inquiry disclosures and ask which checks may apply at each stage. An initial credit inquiry and later payment reporting are separate issues, so review the notices for both.
Are emergency loans ever guaranteed to be approved?
No. A responsible lender cannot promise approval before reviewing your application, so treat any offer of guaranteed approval as a warning sign. The FTC warns against paying a fee for a promise of approval; legitimate fees are disclosed and do not guarantee a loan. Read the actual terms before you agree to anything.
How much will I repay, including fees?
Your loan disclosures show the payment schedule, the total of payments, the APR and any separately payable fees. The finance charge already includes interest and applicable fees, so do not add them again. Check how much cash you will receive, whether a fee is deducted or paid separately and which APR appears in your disclosures. The calculator is an illustration, not a quote. See Rates and Fee Information.
Can emergency loan funds arrive on weekends or holidays?
Weekend or holiday arrival depends on the processing schedule, the transfer method and your receiving bank. Applying does not mean a decision, fund release or deposit happens that day. Funds usually become available within one business day after approval, but timing is not guaranteed. Confirm availability with us and your bank before relying on the money for a bill.
Are emergency loans available in my state?
It depends on where you live. The products we offer, along with amounts, fees, APR limits and terms, follow your state’s law, and eligibility rules can differ too. Start with your state or city page above, then confirm the details in the application. If your state is not listed, contact us to ask; a missing page does not mean you are ineligible.
What should I do if I cannot make a payment?
Contact us before the due date and explain the situation. Your agreement and state law set the options and the consequences of a late payment, so read them carefully. Paying only a renewal fee may leave your principal unchanged, and borrowing again to repay can deepen the shortfall. If you have a problem with a lender, you can submit a financial product complaint.
Ready to apply?
See your loan type, APR and payment dates before you sign.
Approval and funding times are not guaranteed.
Who Reviews Our Loan Information?
Instant Cash Advance publishes this guide to emergency loans. We check the loan descriptions, timing steps and calculator math against official consumer finance sources. Examples are hypothetical and shown with their assumptions. Learn more: About Instant Cash Advance.
Sources and Editorial Updates
State rules, federal guidance and product requirements can change, so confirm current requirements and review your loan disclosures before relying on this guide. If you find an error, use the Report an Error link above. We rely on guidance from the CFPB, the FTC, the NCUA and USAGov, cited in the text above.
General information, not legal or financial advice. Mentions of official sources do not mean those agencies endorse us.


